
 By Reynand Wu
The United Kingdom is rapidly approaching a critical crossroads that could fundamentally define its financial future, according to industry leaders. At the heart of the debate is a pressing question: Should decentralized finance, commonly known as DeFi, be allowed to develop through regulated gateways within the country, or will it be unnecessarily constrained to an isolated silo?
This strategic dilemma extends far beyond the immediate interests of cryptocurrency enthusiasts and digital asset traders. Instead, it strikes directly at the core of the future of capital markets, the international competitiveness of London’s financial sector—widely known as the City—and the United Kingdom’s broader ability to shape and lead the next generation of global financial infrastructure.
For those tracking the evolution of financial technology, DeFi represents a fundamental shift in how transactions occur. It relies on software that enables individuals to borrow, lend, trade, and manage financial assets directly with one another without needing to rely on traditional intermediaries like commercial banks or brokerage firms. Operating less like a traditional financial institution and more like the open internet, DeFi promises to deliver cheaper, faster financial services that remain continuously accessible to anyone around the globe at any time.
While decentralized finance will inherently remain accessible through open-source and purely decentralized routes, regulated financial providers can also serve as a vital bridge to the ecosystem. Through these regulated gateways, everyday customers could engage with the underlying technology while receiving key disclosures about the specific services they are accessing and the distinct risks they should be aware of.
However, regulatory hurdles threaten to upend this cooperative future. Under the Financial Conduct Authority’s (FCA) currently proposed cryptoasset rules, this integration could be rendered entirely impossible. The regulator is expected to require FCA-authorized platforms to ensure that any customer orders are executed strictly on FCA-authorized venues.
Although this mandate is ostensibly designed to prevent overseas firms from illegally accessing the UK market, it simultaneously creates a severe risk of cutting off access to DeFi protocols altogether. This unintended consequence arises because decentralized protocols and automated exchanges where users execute peer-to-peer orders do not feature a centralized corporate entity or individual behind them capable of seeking or obtaining formal regulatory authorization.
While no single rule explicitly states that traditional firms are prohibited from offering DeFi integrations to their retail and institutional customers, the FCA has made its underlying stance clear. Rather than crafting rules tailored specifically to the unique mechanics of these products, the regulator has opted to apply the exact same rigid framework used for fully centralized trading platforms. The practical effect of this approach could easily materialize as a de facto ban.
Without a substantial shift in regulatory strategy, regulated platforms may find themselves legally unable to provide their customer base with access to DeFi services starting in October 2027. This regulatory trajectory stands in stark contrast to official government ambitions. Ministers have repeatedly pledged that they want the United Kingdom to lead the world in the digital asset space. Yet, achieving this lofty ambition will prove exceptionally difficult if British financial firms are systematically blocked from utilizing the decentralized infrastructure upon which modern digital asset markets are built.
DeFi Is Becoming Part of the Next Financial Infrastructure
As the UK deliberates its regulatory posture, financial watchdogs in other major global jurisdictions are already recognizing the immense economic opportunities presented by decentralized technology. These regulators are actively exploring practical frameworks to enable responsible DeFi innovation rather than shutting it out.
Within the European Union, the European Securities and Markets Authority (ESMA) has proposed allowing regulated financial firms to provide client access to DeFi services. The agency noted that such a framework could successfully foster innovation in decentralized finance within a properly regulated and transparent environment.
Similarly, across the Atlantic, the United States Securities and Exchange Commission recently took a notable step by granting an innovation exemption for the peer-to-peer trading of tokenized stocks. This exemption accommodates automated trading systems and liquidity pools, signaling a willingness to adapt.
In short, both the US and the EU are actively investigating how traditional financial systems and emerging DeFi infrastructure can effectively work in tandem. Industry advocates argue that the United Kingdom should be exploring the exact same potential before it decisively closes off this avenue and lags behind international competitors.
Onchain tokenized finance cannot realistically reach its full economic potential if it remains strictly confined to closed, fragmented systems that struggle to interact with the broader decentralized technology underpinning the modern digital economy.
A De Facto Ban May Push DeFi Beyond the Regulator’s Reach
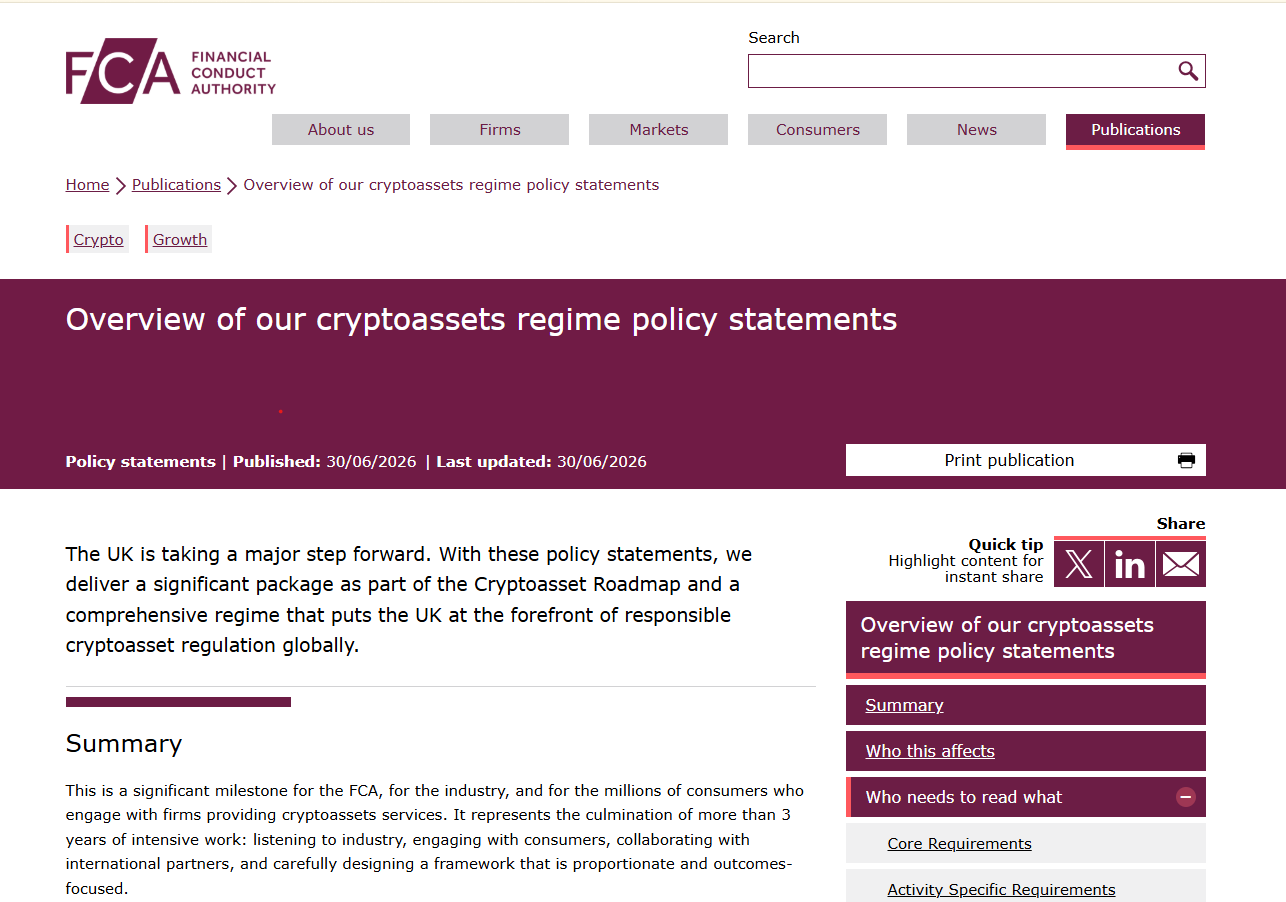
The United Kingdom has officially established its first comprehensive rulebook governing the crypto sector. Beginning Oct. 25, 2027, any firm looking to offer crypto services to UK customers must secure formal authorization from the FCA. To prepare for this milestone, the FCA is currently consulting on specific guidance detailing how its regulatory perimeter will apply to financial services firms that utilize or interact with DeFi applications.
Regulatory concerns surrounding DeFi integrations generally center around three primary risks. First, regulators worry that a retail customer using a familiar, heavily regulated platform might not fully realize when they have crossed over into an environment where standard consumer protections no longer apply. Second, there is apprehension that certain opportunistic firms could attempt to utilize DeFi integrations as a loophole to evade standard regulatory obligations. Third, decentralized finance inherently introduces complex challenges related to financial crime prevention and overall market resilience.
Yet, industry stakeholders emphasize that these genuine risks point directly to the necessity of clear consumer information and well-defined corporate responsibilities—rather than a total prohibition.
Implementing a de facto ban would likely produce the exact opposite of its intended regulatory effect. Rather than eliminating DeFi activity among UK residents, a prohibition would merely push more activity entirely beyond the FCA’s practical visibility. Furthermore, it would severely diminish the ability of regulated domestic firms to guide and protect how everyday customers interact with these protocols.
Regulated platforms can serve as an exceptionally useful focal point for active supervision. They possess the capability to clearly notify customers when they are stepping outside a regulated environment and require explicit user consent before proceeding. Additionally, regulated firms can carefully curate access to vetted protocols, rigorously assess operational and governance risks, and report suspicious incidents and usage patterns directly to regulatory authorities.
Regulate the Gateway, Not the Technology
The concept of regulated institutions providing access to external products or markets that carry varying degrees of oversight is not novel; the UK already embraces this model in other sectors of finance.
A wide variety of retail trading platforms and multi-service super apps currently offer consumers seamless access to an expansive range of financial instruments. These offerings span everything from traditional equities and money market funds to commodities and foreign exchange, each carrying distinct regulatory protections. The FCA routinely permits these mixed-product offerings, provided that the platforms clearly communicate to consumers which specific protections apply to each product and service.
This precedent highlights why DeFi integrations warrant a more nuanced solution. The FCA has a clear mandate to protect consumers, but it should not attempt to achieve that protection through total exclusion.
Enabling responsible integration would yield multiple benefits: it would supply consumers with transparent information, grant supervisors greater operational visibility, and afford UK financial services the competitive opportunity to participate in the next major phase of global financial innovation.
Consumers Will Use DeFi, So the Question Is Where
DeFi protocols are inherently permissionless, meaning they can already be accessed directly by anyone with an internet connection, entirely bypassing traditional regulated intermediaries. Therefore, the central question facing policymakers is not whether consumers will use DeFi, but rather whether they will be permitted to access it through a secure, regulated gateway equipped with clear disclosures and essential guardrails.
The stakes of this decision extend far beyond traditional crypto trading. DeFi underpins the most significant potential cost savings as financial services transition onchain, enabling fewer costly intermediaries and powering resilient systems capable of supporting 24/7 cross-border activity. Establishing regulations that provide a clear, workable route to supporting DeFi is crucial for instilling long-term confidence among firms looking to invest in UK-based financial innovation.
If restrictive access barriers are prematurely imposed within the United Kingdom, the growth of tokenized capital markets and broader financial innovation risks migrating entirely to jurisdictions that take a more decisive approach to supporting decentralized finance infrastructure.
Ultimately, the United Kingdom cannot credibly aspire to be a global leader in digital finance while simultaneously shutting off the foundational decentralized technology upon which the future of global finance is actively being built.
 Layla Zulfa
 Azzam Bilal Chamdy