
 By Laily UPN
"Tokenization is coming to America," declared Robinhood Chief Executive Vlad Tenev after the Securities and Exchange Commission announced its landmark Innovation Exemption. Financial markets clearly welcomed the regulatory milestone, reacting with swift optimism across both traditional and decentralized digital assets.
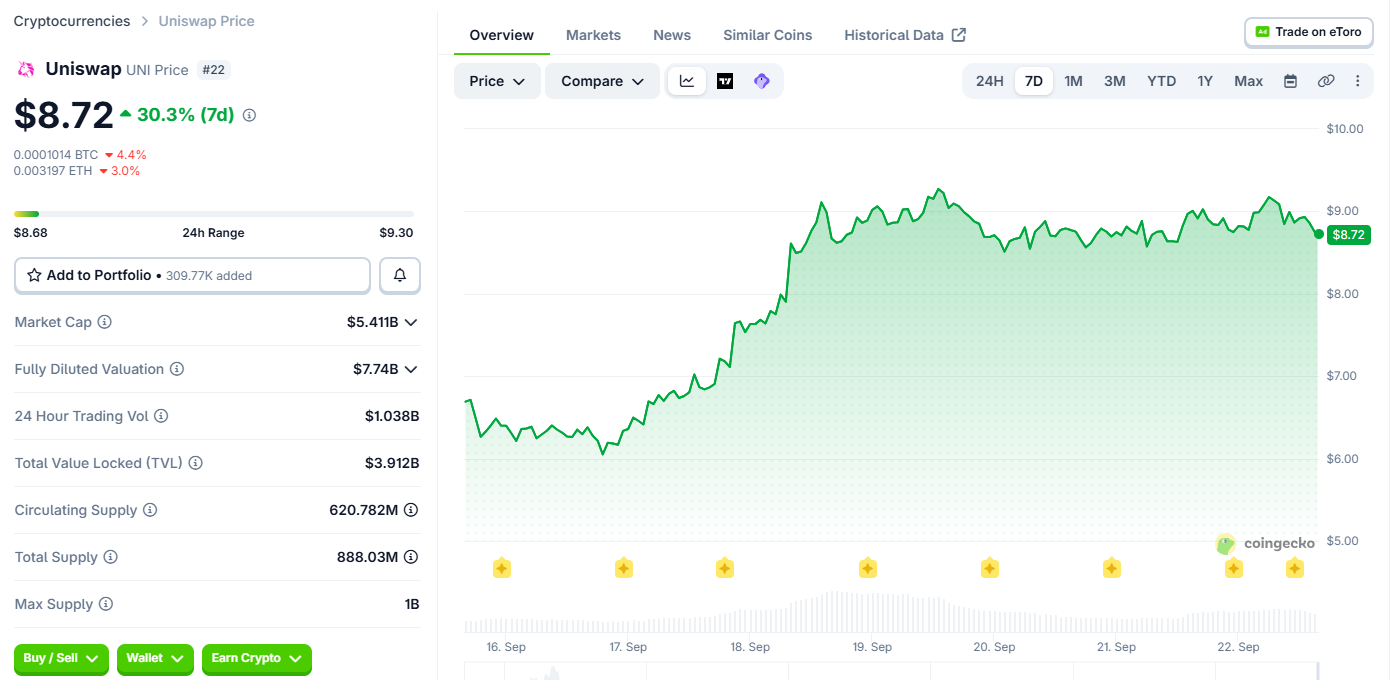
In the immediate aftermath of the announcement, major cryptocurrencies Bitcoin (BTC) and Ether (ETH) surged by over 10%. Meanwhile, decentralized finance protocols experienced even more dramatic inflows. Uniswap’s UNI token—a protocol widely viewed as prime real estate for potential tokenized stock trading—rallied by more than 30% in the days that followed, reflecting intense speculation over how decentralized liquidity pools will interface with regulated traditional equities.
While the Securities and Exchange Commission has indeed greenlit tokenized stocks in the United States, a closer examination reveals that the vast majority of existing stock tokens currently circulating in the market fall outside the boundaries of the new regulatory framework.
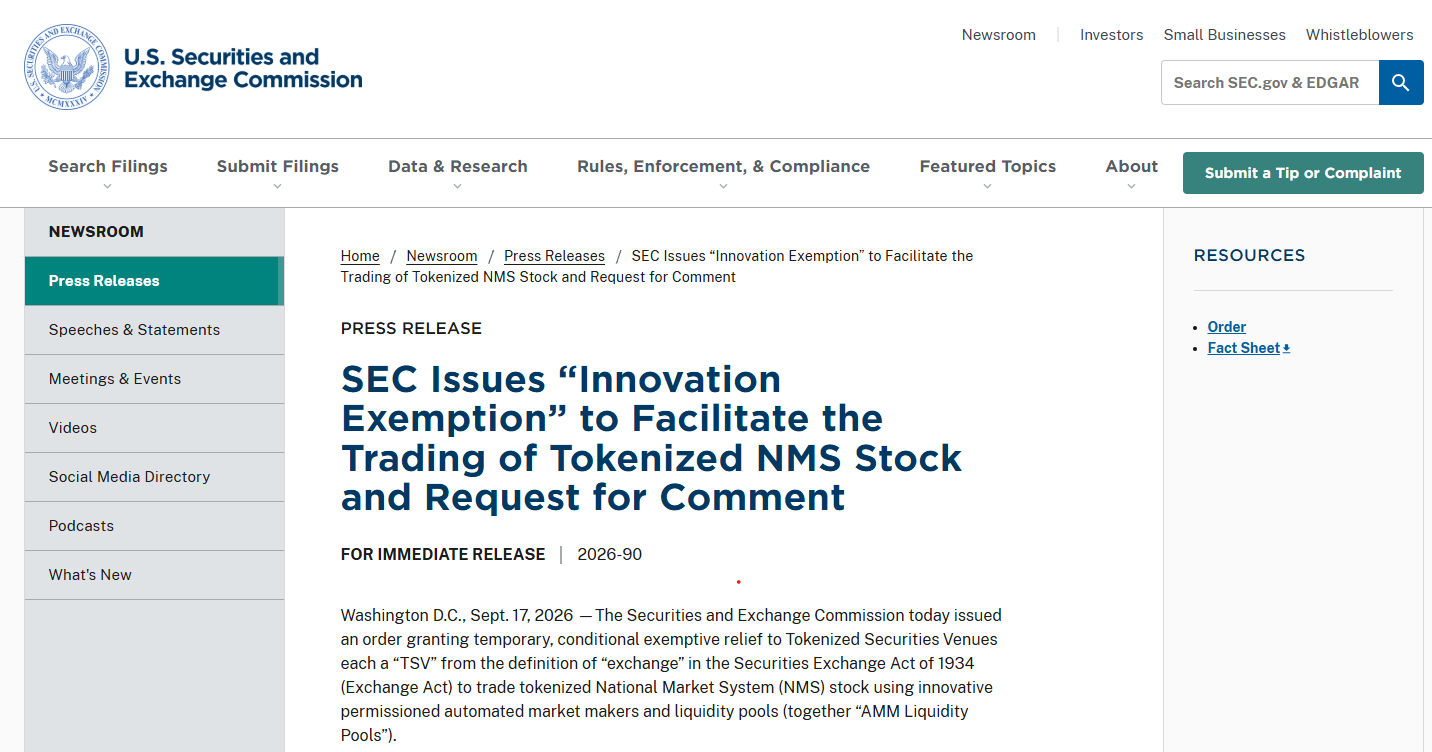
The commission’s newly introduced five-year Innovation Exemption creates a formal, albeit narrow, compliance path for specific trading venues to facilitate the exchange of tokenized National Market System (NMS) stocks onchain without needing to register as traditional securities exchanges. Furthermore, it permits third parties to tokenize equities, but strictly under a predetermined set of conditions.
To maintain compliance under the new rules, tokenized shares must grant holders the exact same rights and privileges as the underlying conventional securities. Additionally, the trading venues hosting these assets are required to implement permissioned user access and strictly controlled liquidity pools.
Not all tokenized equities are created equal in the eyes of regulators. A digital token can easily mimic the appearance of a share and closely track its market price without actually transferring the underlying shareholder rights to the end investor. Under the commission’s updated framework, any asset operating on this basis is classified as a synthetic stock, and it remains entirely non-compliant.
This regulatory distinction means that some of the industry’s biggest players may already possess a structural head start, while others will be forced to rapidly pivot or play catch-up. As Peter Curley, head of global regulatory affairs at Ondo Finance, noted in a discussion regarding the ruling, not every existing strategy will immediately fit the new mold, but the crucial takeaway is that the SEC chose to act proactively rather than waiting indefinitely for congressional legislation.
The SEC’s Tokenization Lane is Narrow
The SEC’s September 17 order provides certain approved trading venues with temporary relief from traditional exchange registration requirements when executing trades of tokenized NMS stocks through permissioned Automated Market Maker (AMM) liquidity pools.
In practical terms, the regulatory agency has successfully carved out a legal lane for onchain stock trading. However, it is a remarkably specific pathway, making the structural architecture of the token just as important as the technological design of the trading venue itself.
To qualify for the exemption, a tokenized stock must ensure that holders receive identical dividends, voting rights, and corporate action benefits as the underlying physical or electronic security. Although third-party entities are permitted to tokenize a stock without a formal partnership with the original issuer, the underlying issuer is granted the authority to veto or reject the token before it becomes eligible for public trading.
This strict requirement effectively rules out synthetic exposure models, spelling immediate bad news for existing products such as Robinhood’s Stock Tokens and Kraken’s xStocks in their current iterations.
During the announcement, SEC Commissioner Hester Peirce emphasized that the temporary exemption covers one particular operational model rather than every conceivable method of trading tokenized securities. Nevertheless, she noted that the agency remains open to exploring alternative models outside of the specific Tokenized Security Venue (TSV) structure as the pilot program progresses.
The Products Closest to the SEC’s Model
Current market offerings from major firms reveal a mixed readiness for the SEC’s framework. Coinbase’s tokenized stock initiatives, for instance, sit relatively close to the required parameters.
On September 14, Coinbase Chief Executive Brian Armstrong stated that the company had established a high standard with its tokenized offerings, emphasizing that they are not synthetic instruments or debt obligations. Instead, he described them as fully backed securities that are redeemable for the underlying shares, complete with integrated dividend mechanics and voting rights scheduled to launch in the near future.
Despite these features, Coinbase’s existing tokenized stock offerings are primarily targeted at non-US customers, and the company’s core exchange infrastructure relies on a traditional central limit order book rather than the permissioned AMM liquidity pools favored by the SEC’s exemption. However, because Coinbase operates the Layer-2 network Base, it retains substantial flexibility to adapt its infrastructure.
Meanwhile, Ondo Finance launched tokenized US securities earlier in June. Under this structure, the underlying shares are held in traditional institutional custody, while the digital token represents the investor’s legal entitlement onchain.
Ondo also completed the acquisition of Oasis Pro, a corporate entity that includes an SEC-registered broker-dealer, an Alternative Trading System (ATS), and a transfer agent, creating an integrated bridge across both traditional and decentralized financial markets.
Curley pointed out that the SEC’s exemption explicitly favors the exact model Ondo has already proven out: custodial, entitlement-based systems featuring real shareholder rights and corporate actions that pass directly through to the ultimate token holder. Even so, he cautioned that the firm is not operating under the assumption that existing setups will receive automatic regulatory clearance.
Ultimately, while both Coinbase and Ondo possess critical pieces of the technological infrastructure the SEC desires, neither can assume their current operational setups comply fully without minor adjustments and structural finessing.
Uniswap’s Permissioned Pools Could Open the Door
Because the SEC’s exemption is explicitly tailored around permissioned AMM liquidity pools, the regulatory shift appears to present significant opportunities for decentralized exchange protocols like Uniswap.
Uniswap introduced Permissioned Pools for its v4 architecture, allowing regulated financial assets to trade through AMMs with compliance protocols enforced directly onchain. While this feature does not automatically designate Uniswap itself as a recognized TSV, its v4 infrastructure can easily be utilized by market operators seeking to build one. Because Permissioned Pools allow asset issuers to exert precise control over who is permitted to trade or provide liquidity, the technical framework aligns closely with the SEC’s stringent mandates.
Permissioned access typically requires robust Know Your Customer (KYC) verification, comprehensive record-keeping protocols, public notices, and transactional transparency. If these decentralized operational layers can be successfully connected to the traditional shareholder rights and regulatory reporting frameworks required for US securities trading, Uniswap possesses a foundational architecture that could be adapted to meet the SEC’s vision.
Robinhood Has the Users, But Not the Right Product
Robinhood already boasts roughly 200 stock tokens actively trading on its proprietary Robinhood Chain, a network that Tenev has frequently described as being backed on a one-to-one basis and fully composable within the decentralized finance ecosystem.
However, Jaewon Kim, head of research at Four Pillars, pointed out that the SEC’s exclusion of synthetic exposure effectively disqualifies prominent products like Robinhood’s Stock Tokens and Kraken’s xStocks.
Robinhood’s Stock Tokens are technically structured as tokenized debt securities issued by Robinhood Assets (Jersey) Limited. Consequently, while they provide investors with economic exposure to the underlying equities, they do not confer direct legal or beneficial shareholder rights. Furthermore, these products are not registered under US securities laws and remain unavailable to US persons.
Nevertheless, while Robinhood’s existing product lineup does not conform to the new SEC rules, its massive retail user base and advanced blockchain infrastructure could provide the company with a distinct competitive advantage if it decides to reconfigure its model to meet the updated compliance standards.
Kraken’s xStocks face a similar hurdle. Although they are fully backed by underlying equities, they similarly fail to grant holders the precise legal rights associated with conventional shares. Under the terms of the new exemption, mere backing by physical shares is insufficient to qualify without the accompanying legal privileges.
Bryan Choe, head of research and operations at RWA.xyz, a market intelligence platform specializing in tokenized real-world assets, noted that while the majority of existing tokenized equity products are currently sponsored by third parties, that dynamic is likely to shift dramatically over the coming year.
Choe explained that market participants expect a widespread transition toward issuer-sponsored models, noting that the new exemption successfully aligns token issuers directly with underlying stock issuers, which could bring greater balance and regulatory certainty to different issuance methodologies.
Five Years to Prove Tokenized Stocks Are Actually Better
The SEC has explicitly framed the Innovation Exemption as a temporary measure. Commission Chairman Paul Atkins noted that the five-year evaluation window will provide the broader market with adequate space to innovate and develop while the regulatory body carefully evaluates future rulemaking initiatives.
Beyond the race to establish the first fully compliant trading venue, the ultimate test for the industry is whether tokenized equities can demonstrate tangible utility and capture widespread market adoption.
As Curley emphasized, retail and institutional investors must ultimately be provided with a product that is demonstrably faster, cheaper, and more useful than a conventional brokerage position. Industry analysts have already raised questions regarding whether fragmented liquidity across various tokenized stock offerings will be capable of supporting tight pricing spreads and a seamless user experience.
The regulatory exemption holds the theoretical potential to unlock continuous 24/7 trading, fractional ownership, accelerated settlement times, onchain composability, and direct shareholder rights. However, these technological advantages will only matter if market participants ultimately find them superior to legacy financial systems.
 Jia Lissa
 Layla Zulfa